Free Mortgage Calculator & Home Loan Tools
Estimate monthly payments with principal, interest, taxes, insurance, and PMI. Compare loan types and see how much house you can afford — in your browser, for free.
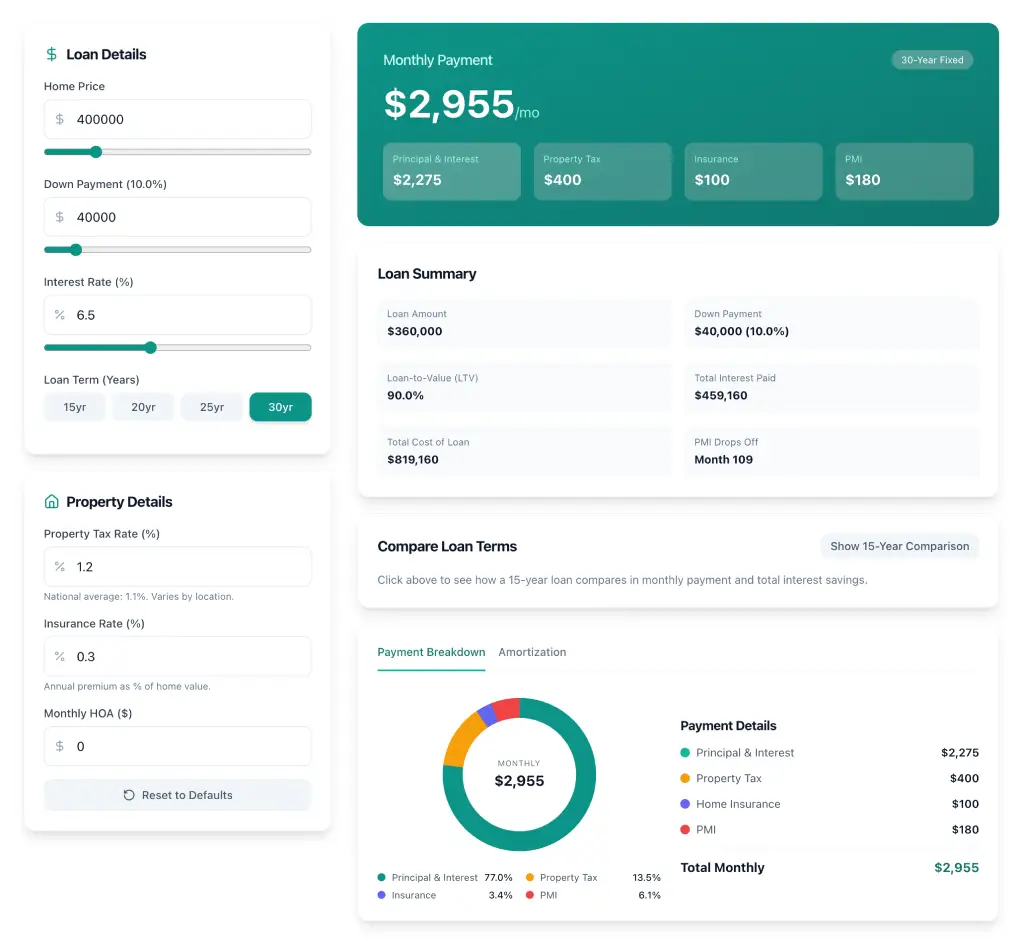
Quick Answer: A mortgage calculator estimates your monthly home loan payment by combining the principal loan amount, interest rate, loan term, property taxes, homeowners insurance, and PMI (if your down payment is under 20%). For a $350,000 home with 10% down at a 6.5% interest rate on a 30-year loan, your estimated monthly payment would be approximately $2,460 including taxes and insurance.
Payment tools on this site
Each tool is free, runs locally in your browser, and uses the formulas on our methodology page. Default interest figures are examples — not a live weekly survey.
Payment estimator
Monthly principal, interest, taxes, insurance, PMI, and HOA from inputs you control.
PITI + PMIHow Much House Can I Afford?
Find a maximum home price from income, debts, and a 28/36-style DTI cap.
28/36-style DTIVA Loan Calculator
Funding fee, residual income, and a payment estimate for qualifying veterans.
Funding fee modelRefinance Calculator
Current vs new rate, remaining term, and months to break even on closing costs.
Break-even estimateFHA Loan Calculator
FHA-style payment with upfront and annual MIP included in the illustration.
MIP includedAmortization Schedule
Chart plus month-by-month principal vs interest, with optional extra payments.
Full schedule30-Year Mortgage Calculator
Payment on a 30-year fixed loan, with taxes and insurance included.
30-year fixed15-Year Mortgage Calculator
Higher monthly payment, less interest than a 30-year loan.
15-year fixedPayment on a $300,000 House
Worked monthly payment for a $300k purchase, including a 7% example.
$1,597 P&I at 7%What each estimate includes
Many simple tools show only principal and interest. Ours also adds the other lines that usually appear in a monthly housing payment — because a real bill is rarely just P&I.
- Principal & Interest — Based on loan amount, interest rate, and term
- Property Taxes — Estimated from your home value and location
- Homeowners Insurance — Typical rates for your home value
- PMI (Private Mortgage Insurance) — Automatically calculated if down payment < 20%
- HOA Fees — Optional — add if your property has them
Sample Calculation
Including principal, interest, taxes, insurance, and PMI (rounded)
Worked example documented on methodology. Default 6.5% is an illustration, not this week’s PMMS average.
Guides and explainers
Plain-language notes on DTI, PMI, closing costs, and related topics
PMI Rate Guide: 7 Honest Factors Lenders Price In
Sep 12, 2026
When Can I Cancel PMI? 5 Critical 80% / 78% Rules
Sep 12, 2026
Mortgage Recasting vs Extra Payments: 6 Money Tradeoffs
Sep 12, 2026
Are VA Loans Hard to Get?
Aug 25, 2026
Do VA Loans Have PMI?
Aug 25, 2026
VA Funding Fee vs PMI
Aug 25, 2026
The 28/36 Rule Explained
Jan 15, 2026
What is PMI and How to Avoid It
Jan 22, 2026
How to Calculate Your Mortgage Payment
Feb 1, 2026
VA Loan Eligibility Requirements
Feb 8, 2026
Documented formulas
Amortization, PMI bands, and tax defaults are published on the methodology page.
Editorially reviewed
Organization byline — no invented CFA/CFP person or fake testimonials.
Free and private
No signup. Calculator inputs stay in your browser.
Common questions
Estimates, PITI, affordability rules, and PMI